The rapid growth of zero-days-to-expiration (0DTE) options is transforming the US derivatives market, bringing new opportunities for traders while raising important questions about how risk is measured, understood, and communicated. As same-day options become an increasingly significant part of trading activity, the need for more sophisticated, transparent, and accessible risk analytics has never been greater.
For many traders, evaluating an options strategy still comes down to a handful of familiar metrics: strikes, premiums, margin requirements, and probability of profit. Yet these figures rarely tell the full story. A strategy with a high probability of success can still carry substantial downside exposure, making it essential to understand not only the likelihood of a favorable outcome, but also the potential consequences when the market moves against the position.
This is the challenge behind dxFeed ZeroDTE, a new quantitative analytics solution developed by dxFeed’s AI & Quant Research team. Built on live options market data, the technology translates complex market-implied probabilities into intuitive pricing and risk insights, helping brokers, trading platforms, and analytics providers give traders a more complete picture of potential outcomes before entering a trade.
Rather than simply displaying what a trade might earn, the solution reveals what current market prices imply about its risks, from the likelihood of retaining the full premium to the probability of partial or maximum loss. It brings sophisticated quantitative analysis closer to the trading decision, making the information already embedded in options prices more accessible, consistent, and actionable.
Addressing a Growing Gap in the 0DTE Options Market
The launch comes as same-day options trading continues to reshape US derivatives markets. According to Cboe, 0DTE contracts accounted for approximately 65%* of total SPX options trading volume in the third quarter of 2026, reaching a record average of 3.2 million contracts per day. Retail participation has also become a defining feature of this market, accounting for 54% of SPX 0DTE volume in May 2025.
Yet the rapid growth of these instruments has not always been matched by equally sophisticated risk analytics available to individual traders. As Jon Light, Senior Director of Product Management at Devexperts, highlighted in his article “What Retail Options Trading Means for the Broader Market”, the increasing accessibility of complex options strategies calls for more advanced risk modeling, pre-trade controls, and greater transparency around potential losses.
Strategies such as iron condors, butterflies, and credit spreads can offer attractive probabilities of retaining the premium while exposing traders to substantially larger potential losses. Understanding the probability of success without considering the magnitude and likelihood of adverse outcomes can therefore create an incomplete picture of the trade.
ZeroDTE addresses this challenge by bringing institutional-grade quantitative analysis into the trading interface, making complex options pricing and risk information easier to interpret and compare.
Turning Live Market Data into Meaningful Risk Intelligence
Unlike conventional probability calculations that may rely on a single implied volatility estimate or an option’s delta, ZeroDTE analyzes the entire live 0DTE options chain, incorporating the volatility smile and distribution tails to derive a consistent, market-implied probability distribution for the underlying index’s closing price.
Built on dxFeed’s existing OPRA market data infrastructure, the service currently supports same-day SPX and XSP options and a range of widely used strategies, including straddles, strangles, vertical spreads, butterflies, and iron condors.
Through a single API request, trading platforms can retrieve:
- Market-implied outcome probabilities: The likelihood of retaining the full premium, experiencing a partial loss, or reaching the maximum loss.
- Fair value versus market price: A consistent pricing reference for evaluating option structures against displayed quotes.
- Maximum profit and loss: Clearly defined potential outcomes, including the full downside exposure of a strategy.
- Break-even levels: The underlying price levels at which a position transitions between profit and loss.
- Market-implied distribution of today’s close: A visual representation of the range of outcomes implied by current options prices.
- Volatility-adjusted strategy comparisons: Standardized strike distances based on the day’s priced market movement, allowing traders to compare equivalent strategies across different volatility environments.
By combining these metrics in a single analytical framework, ZeroDTE enables traders to evaluate not only how likely a strategy is to succeed, but also what is at stake when it does not.
The solution is designed to integrate directly into trading terminals, broker platforms, and analytical applications through a documented REST API, allowing financial technology providers to deliver sophisticated risk intelligence without building proprietary quantitative pricing infrastructure.
From Market Data to Decision Intelligence
One of the solution’s distinguishing capabilities is its ability to translate complex mathematical models into intuitive, trader-facing information.
For example, an iron condor may show an 89% market-implied probability of retaining its premium, while still exposing the trader to a potential loss many times greater than the premium received. Presenting both figures together provides a more meaningful basis for evaluating the trade than probability alone.
The service also standardizes options structures using the market’s priced daily movement rather than fixed index-point distances. This allows platforms to offer consistent strategy presets across different market conditions, making comparisons more meaningful whether volatility is relatively subdued or elevated.
Importantly, the analytics represent probabilities implied by current market prices, not predictions of future market movements or claims of trading advantage.
The underlying model is designed to maintain internal pricing consistency and includes safeguards that withhold calculations when available market quotes are insufficiently reliable.
“Same-day options have become a major part of the market, but understanding the risks behind these strategies remains unnecessarily complicated for many traders,” said Dmitry Zotikov, Lead Quantitative Analyst at dxFeed. “Our objective is to make the information already embedded in options prices accessible and useful. A trader should be able to see not just the potential reward, but the market-implied likelihood and scale of the risks they are taking. That transparency is what better trading technology should deliver.”
Expanding dxFeed’s Intelligent Market Data Ecosystem
ZeroDTE represents another step in dxFeed’s continued expansion beyond traditional market data delivery into advanced analytics, quantitative research, and intelligent financial technology solutions.
The company’s growing portfolio includes SummerFox, its award-winning AI-powered market intelligence and reporting solution; Grenadier, an AI-based market data anomaly detection technology; and dxScript, a JavaScript-based scripting environment with an integrated AI assistant that enables traders and developers to build custom indicators, analytics, and trading logic.
Together, these technologies reflect dxFeed’s broader strategy to transform high-quality financial data into increasingly accessible, programmable, and actionable intelligence.
With SummerFox supporting market intelligence, Grenadier detecting anomalies in the live order book, dxScript expanding analytical flexibility, and ZeroDTE bringing sophisticated options pricing and risk analytics closer to the point of execution, dxFeed continues to build a comprehensive technology ecosystem serving the evolving needs of financial institutions, brokers, platforms, and professional market participants.
“Financial markets are generating more data than ever, but the real opportunity lies in making that data more meaningful and usable,” said Stepan Bolshakov, Managing Director at dxFeed. “We are expanding our capabilities across AI, quantitative analytics, and programmable technologies to help our clients build smarter financial products. ZeroDTE is a natural extension of that strategy, combining our market data expertise with advanced quantitative research to address a clear and growing industry need.”
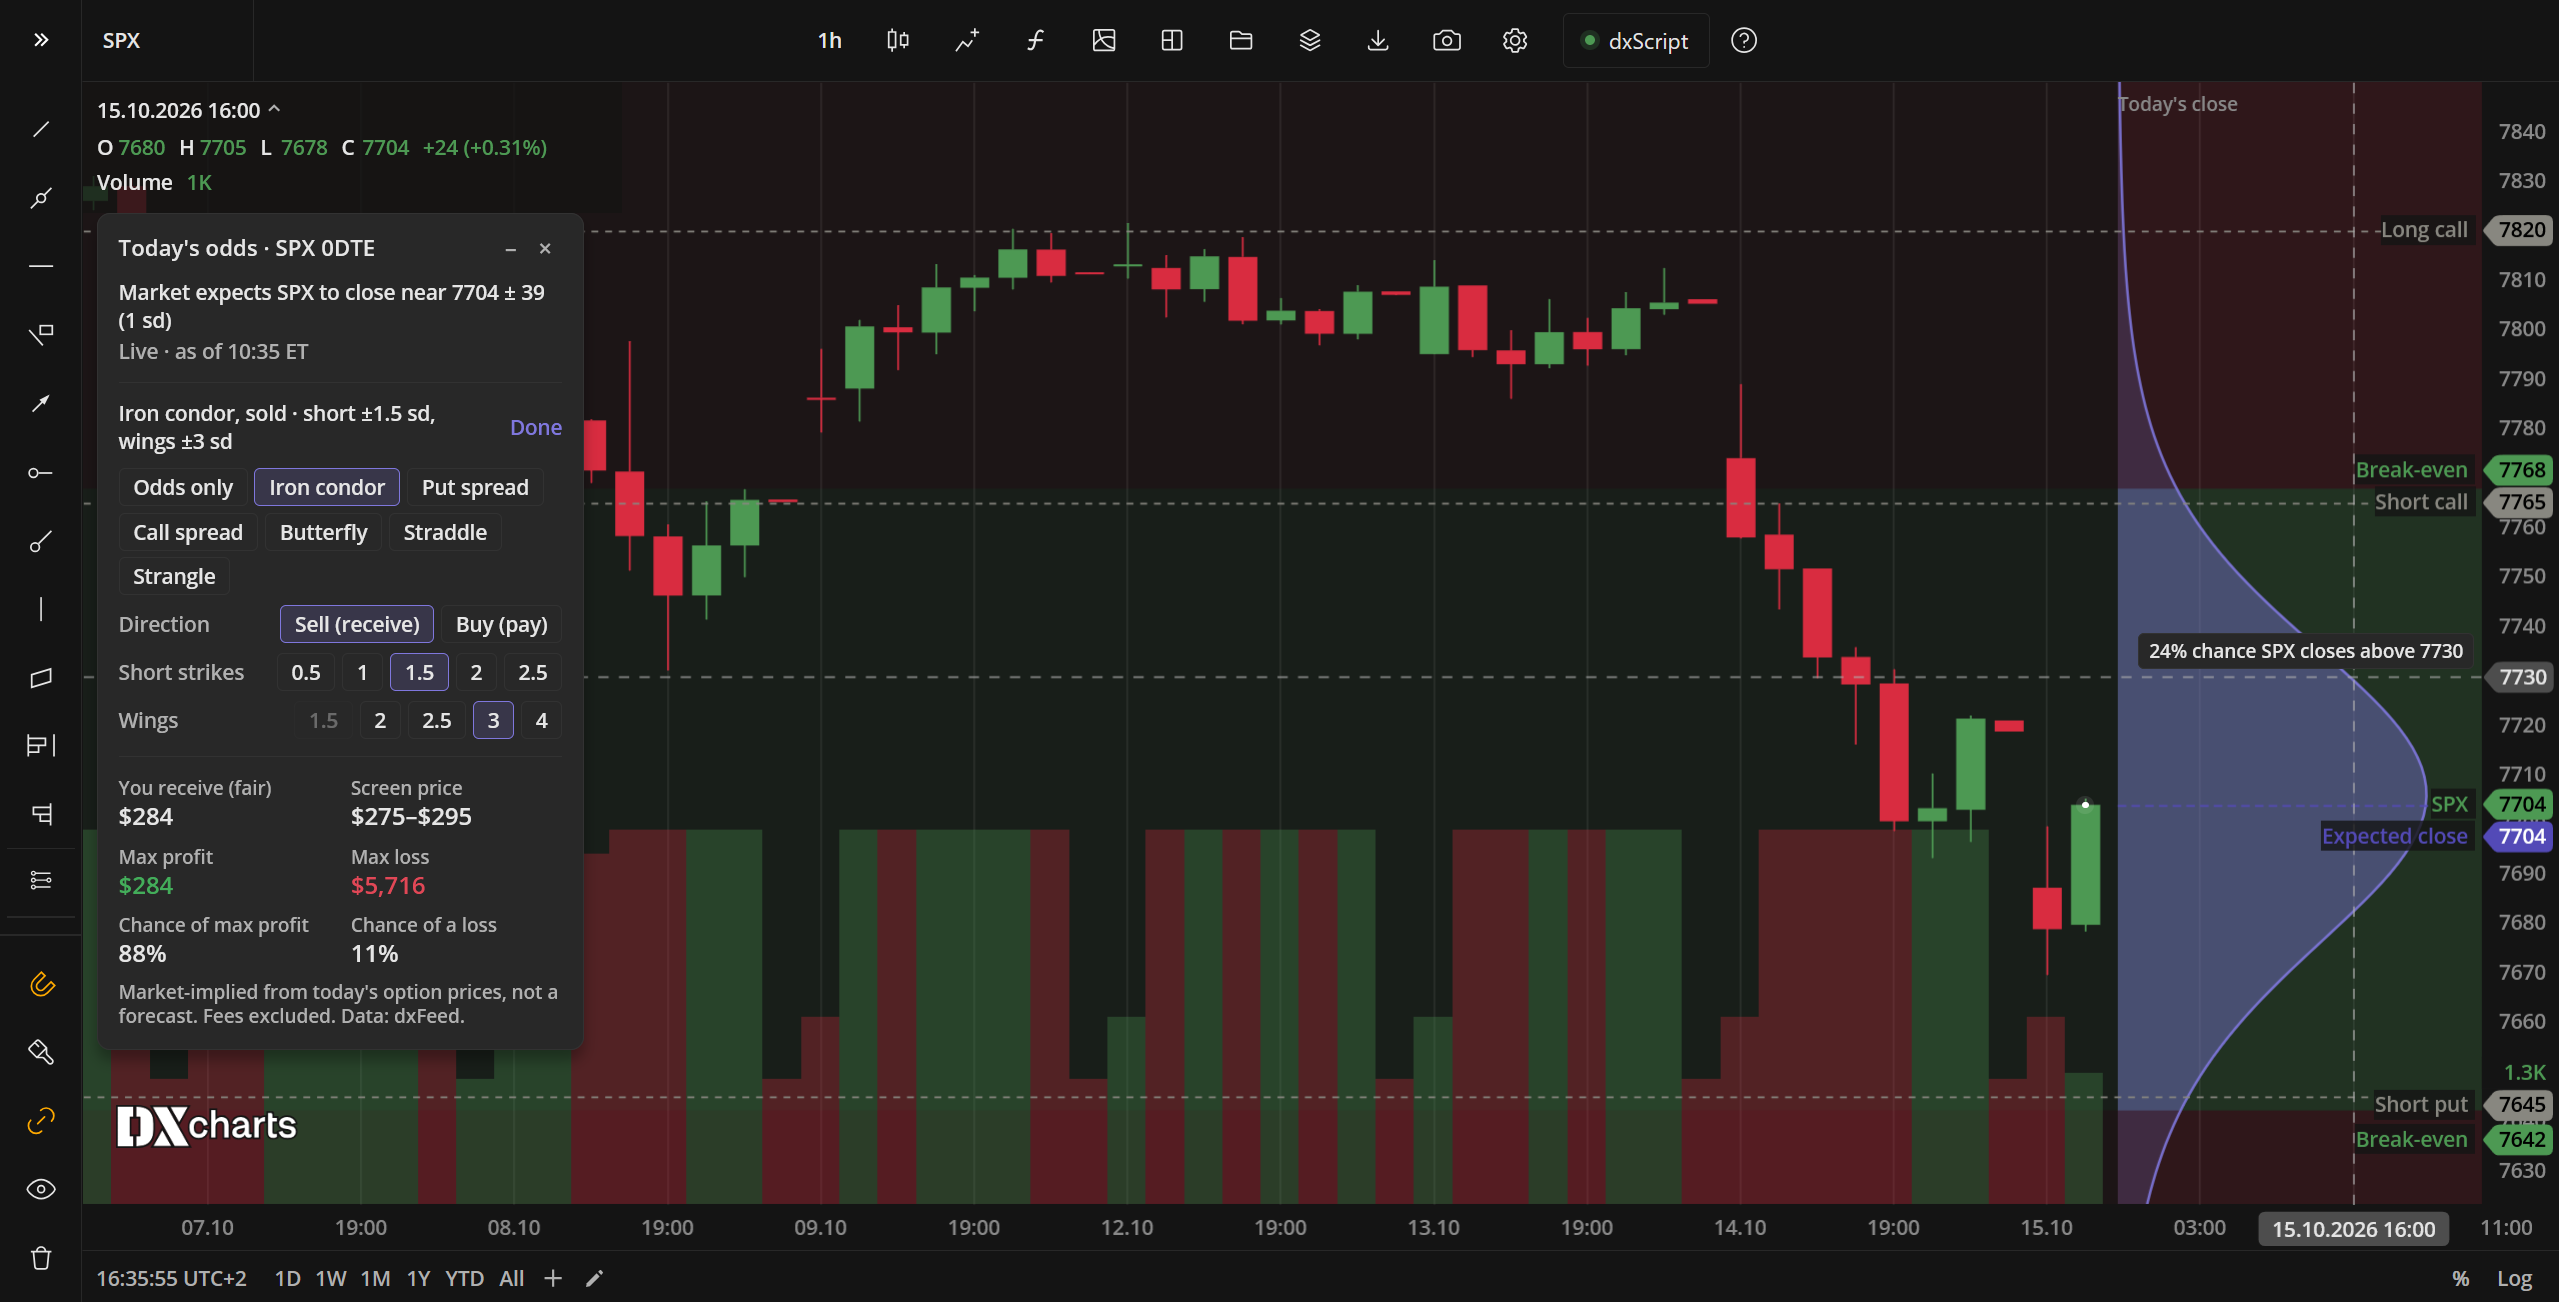
The new analytics capabilities have already been integrated into DXcharts, demonstrating how market-implied probability distributions and strategy-level risk metrics can be incorporated directly into a charting experience. There, the service appears as the Today’s Odds panel: the market’s distribution of today’s close is drawn on the price axis, the structure’s strikes and break-evens are marked on it, and the trader picks a structure and sd distances rather than typing strikes.
Further details on commercial availability and integration options will be announced separately.
*All figures are market-implied from current option prices and are not a forecast or a recommendation
Related articles: